(Revised version: October 2026)
Five years after Brexit, the United Kingdom remains an attractive market for European online retailers. However, shipping across the English Channel has become more complex. Customs declarations, import sales tax, proofs of origin, and additional security requirements are now part of everyday shipping operations.
Anyone selling goods from Germany or other EU countries to British end customers must therefore consider more than just shipping costs and delivery times. Incomplete customs data, incorrectly declared goods, or unresolved import duties can lead to delays, additional costs, and dissatisfied customers. The questions of who is responsible for customs clearance and what costs the recipient will incur should also be clearly answered before shipment.
At the same time, the British market remains economically significant for many e-commerce companies. With a well-thought-out shipping strategy, accurate data, and the right logistics partners, it is possible to meet these additional requirements and efficiently organize international shipping processes.
What customs and tax rules will apply in 2026 for shipments to the United Kingdom? When are import duties due? And what should online retailers keep in mind to ensure their packages arrive reliably at their customers’ doorsteps?
Brexit and Shipping to the United Kingdom: The Most Important Information at a Glance
- Customs formalities remain mandatory. For regular shipments of goods from the EU to England, Scotland, and Wales, customs declarations are generally required. Duty-free importation does not mean that these formalities are waived.
- The 135 GBP threshold affects VAT. For many direct B2C sales with a shipment value of 135 GBP or less, UK VAT is already collected at the time of sale. Above this threshold, standard import procedures generally apply.
- Not all goods from the EU are automatically duty-free. The trade agreement between the EU and the United Kingdom allows for duty-free treatment of goods that meet the applicable preferential rules of origin. Simply being shipped from an EU country is not sufficient for this.
- Additional security declarations are part of the shipping process. As of January 31, 2025, ENS security declarations are generally required for imports from the EU to the United Kingdom, unless an exception applies. Legal responsibility generally lies with the carrier.
- Accurate shipping information helps prevent avoidable problems. Correct product descriptions, tariff codes, declared values, and country-of-origin information streamline the process and reduce the risk of unnecessary delays.
How has Brexit affected shipping to the United Kingdom?
As of January 1, 2021, the United Kingdom is no longer part of the EU single market or the EU customs union. Since then, shipments of goods to England, Scotland, and Wales have been considered exports to a third country. For European online retailers, this means additional customs formalities and stricter requirements for shipping processing.
In addition to the usual shipping information, customs-related details such as a description of the goods, the tariff code, the value of the goods, and their country of origin are therefore required. If this information is incomplete or incorrect, customs clearance may be delayed.
The Free Trade Agreement: Duty-Free Does Not Mean Without Customs Formalities
The Trade and Cooperation Agreement (TCA) between the EU and the United Kingdom allows for the trade of goods without import duties under certain conditions.
However, it is crucial that the goods meet the applicable preferential rules of origin and that the duty exemption is claimed correctly. Even for duty-free goods, the required customs declarations still apply.
Source: European Commission, the EU, and the United Kingdom
Why the Origin of Goods Is Crucial
The country of shipment and the country of origin are not the same. For example, a product manufactured in Vietnam and subsequently shipped to the United Kingdom from a German warehouse does not automatically qualify for preferential EU origin status.
For goods that are manufactured in the EU or have undergone sufficient working or processing, a tariff preference may be available. The decisive factors are the product-specific rules of origin and the required documentation.
Further information: HMRC, Rules of Origin
Case Study: Sneakers from Vietnam
An online retailer stores goods produced in Germany or imported into Germany and ships them to the United Kingdom. The key factor in determining eligibility for a customs duty reduction is not the location of the warehouse, but whether the goods in question meet the preferential rules of origin.
Key point: The country of shipment and the country of origin are not the same.
What customs and tax rules will apply in 2026 for shipments to the United Kingdom?
For European online retailers, customs duties and taxes have been among the most important factors in shipping planning since Brexit. The key considerations are not only the types of goods being shipped, but also their value, their origin, and who is responsible for handling import clearance.
Especially when shipping directly to British end customers, retailers must ensure that VAT, potential customs duties, and additional fees are correctly accounted for. Otherwise, unexpected costs may arise that only become apparent upon delivery.
The 135 GBP Threshold: What Are the Rules for Smaller B2C Shipments?
The shipment value of 135 British pounds (GBP) plays a key role. For many shipments of goods from the EU to England, Scotland, and Wales, different value-added tax procedures apply depending on whether this value is exceeded.
For direct B2C sales with a shipment value of up to and including 135 GBP, British Value Added Tax (VAT) is generally collected at the time of sale. The merchant is then generally responsible for complying with the relevant British VAT obligations. This may also include registering with the British tax authority, HMRC.
If the goods are sold through an online marketplace, the marketplace may be responsible for collecting and remitting VAT instead.
Important: The £135 threshold refers to the taxable value of the entire shipment, not the price of a single item. Special valuation rules apply when determining this value, such as for separately listed shipping costs.
In addition, low-value shipments are currently exempt from import duties under certain conditions. However, this does not mean that these goods are generally tax-free or that they do not have to comply with customs requirements. Special rules apply to certain categories of goods, particularly those subject to excise taxes.
Source: HMRC – VAT and overseas goods sold directly to customers in the UK
What happens with shipments over 135 GBP?
If the applicable shipment value exceeds the threshold of 135 GBP, the standard U.K. import procedures generally apply. In this case, import sales tax and any applicable customs duties are handled as part of the import process.
Whether import duties are actually incurred depends, among other things, on the type of goods, the tariff code, and the preferential origin of the goods. Under certain conditions, the trade agreement between the EU and the United Kingdom may allow for duty-free imports.
Regardless of this, UK value-added tax (VAT) is due in accordance with the applicable tax rules. The standard UK VAT rate is 20 percent. Reduced tax rates or tax exemptions apply to certain goods.
For online retailers, it is also important to determine who is responsible for paying import duties and any applicable customs clearance fees. These responsibilities should be clearly defined before shipment.
British VAT: A Comparison of the 135 GBP Threshold
Simplified overview for standard B2C shipments to England, Scotland, and Wales. Special cases are not included.
DDP or DAP: Who Pays the Import Duties?
In addition to the actual customs and tax regulations, the agreed-upon delivery model also influences the shopping experience.
Under DDP (Delivered Duty Paid), the seller is generally responsible for handling import formalities, including the applicable duties. For the recipient, this can have the advantage that the relevant costs are taken into account before delivery.
Under DAP (Delivered at Place), the buyer is generally responsible for import clearance and the corresponding import duties. This may result in additional costs for end customers at the time of import or prior to delivery.
However, these shipping terms do not supersede statutory sales tax regulations. In particular, VAT obligations for B2C shipments up to 135 GBP must be properly fulfilled regardless of these terms.
It is therefore crucial for merchants to choose a shipping model in which responsibilities, additional costs, and payment processes are clearly defined. Transparency at checkout can prevent customers from being confronted with unexpected fees upon delivery.
ENS: Additional security registrations since January 2025
In addition to customs declarations, security requirements must also be taken into account when importing goods into the United Kingdom.
As of January 31, 2025, so-called Entry Summary Declarations (ENS) are generally required for imports from the EU into the United Kingdom, unless a statutory exception applies.
These security declarations enable British authorities to screen the movement of goods for potential risks even before their arrival.
Legal responsibility for timely submission generally lies with the carrier or the responsible transportation company. However, the declaration may be submitted by an authorized service provider with the carrier’s consent.
For online retailers, this does not automatically mean that they must submit every ENS themselves. They should, however, ensure that their shipping partners meet the requirements and receive all necessary shipment information in a timely manner.
Source: HMRC – Safety and Security Declarations
Why Data Quality Is Crucial in Customs Clearance
Regardless of the value of the goods and the delivery method, the quality of the information provided is a key factor in ensuring smooth shipping processes.
This includes, in particular:
- Clear and complete descriptions of goods
- Correct customs tariff codes
- Verifiable declared values
- Information on the origin of goods
- Required sender and recipient information
- Additional permits or product-specific documentation, if applicable
If this information is missing or is submitted incorrectly, it may result in follow-up inquiries, delays, or additional costs.
Therefore, especially when sending international packages on a regular basis with many individual orders, merchants should rely on automated data transfers and reliable coordination between their online store, inventory management system, and shipping provider.
Outlook: New Customs Rules Planned for Low-Value Imports
The British government has announced further changes to the rules governing so-called low-value imports, effective in 2026. The current import duty exemption for goods valued at up to 135 GBP is to be abolished and replaced by new customs procedures.
According to the plans published in July 2026, the new regulations are to be implemented by October 2028 at the latest. The specific procedures and technical requirements are still being finalized.
For online retailers, this means that the current £135 regulations should continue to be followed. At the same time, it is advisable to take the announced changes into account early on when planning international shipping processes.
Source: HMRC – Reforming customs rules for low value imports
Great Britain is not the same as Northern Ireland: Different shipping rules
England, Scotland, and Wales together make up Great Britain. For shipments of goods from the EU, the customs formalities introduced after Brexit apply there. Northern Ireland is also part of the United Kingdom but has a special status regarding the movement of goods with the EU.
The Windsor Framework governs the movement of goods
Under the special arrangements for Northern Ireland, key EU regulations governing the movement of goods and value-added tax continue to apply there. Therefore, when goods are shipped directly from the EU to Northern Ireland, neither customs declarations nor ENS security declarations are generally required.
Value-added tax is also treated differently than for shipments to Great Britain. For sales to private customers, the rules on intra-Community distance sales and the One-Stop-Shop (OSS) procedure may apply. The UK’s 135-GBP rule therefore cannot simply be applied to Northern Ireland.
The actual route of transport remains the decisive factor. For example, if goods are transported to Northern Ireland via Great Britain, additional requirements may apply.
For online retailers, this means that Great Britain and Northern Ireland should be treated as separate destination areas as early as the shipping planning stage.
Sources: European Commission, Windsor Framework | HMRC, Trade in Goods with Northern Ireland
What does this mean for online retailers?
Therefore, the same requirements do not automatically apply to shipments to Northern Ireland as they do to packages sent to London, Manchester, or Edinburgh.
For example, the £135 threshold for British VAT explained earlier cannot be applied across the board to direct shipments of goods from the EU to Northern Ireland.
The actual shipping route and the type of goods are also crucial. For example, if shipments are transported to Northern Ireland via the United Kingdom, additional requirements may apply. Special regulations also apply to certain categories of goods.
Online retailers should therefore distinguish between destination regions as early as the shipping planning stage and ensure that their shipping processes take the respective requirements into account.
Conclusion: The United Kingdom is not a completely uniform customs territory when it comes to parcel delivery. By distinguishing correctly between Great Britain and Northern Ireland, you can avoid unnecessary formalities and organise your international dispatch processes more effectively.
Further information: HMRC – Trading and moving goods in and out of Northern Ireland
What impact will Brexit have on shipping and logistics?
Brexit has not necessarily lengthened transport routes, but it has changed the processes involved between ordering and delivery. Customs clearance, data transfer and additional requirements must now be taken into account when planning shipments.
For online retailers, this primarily affects delivery times, costs, customer transparency and returns.
Delivery times: More than just the duration of transport
How quickly a parcel arrives in the UK from Germany depends on the route, the delivery partner and the volume of parcels. Since Brexit, customs clearance has also played an important role.
Not every consignment is physically inspected or automatically delayed. However, incomplete information and additional checks can prolong the entire process.
Online retailers should therefore not only consider the transit time, but also calculate realistic delivery times for the entire supply chain.
Delivery charges and transparency: what customers actually pay
The base parcel price does not always reflect the full delivery costs. Depending on the delivery method, additional charges may apply for customs clearance and other services.
It becomes particularly problematic when customers only find out about additional costs upon delivery. This can lead to refusals to accept parcels, returns and increased support workload.
Transparent information on delivery times, potential additional costs and a clear tracking service are therefore key components of a good international shopping experience.
Data quality: International logistics starts with the online shop
Missing customs information or incorrect product data can delay dispatch. With larger volumes of shipments, manually correcting such errors quickly becomes an operational problem.
For this reason, relevant information should be transferred as automatically as possible between the online shop, the stock management system, the dispatch software and the logistics provider.
International shipping processes are not made efficient by a fast carrier alone, but through the interplay of data, systems and operational processing.
Returns: The return journey also takes you across a customs border
If a British customer returns their order to a European online retailer, the goods must cross a customs border once again. An international return is therefore not comparable to a standard domestic return.
Under certain conditions, goods originally exported from the EU may be treated as returned goods upon re-importation. This may result in customs duty exemptions and, where applicable, exemption from import VAT.
The requirements include, amongst other things, appropriate evidence of the original export, compliance with the relevant conditions for returned goods, and correct declaration upon re-importation.
It is therefore worthwhile for online retailers to take the returns process into account right from the initial dispatch. Clear returns instructions, complete shipment details and coordinated customs clearance help to reduce additional administrative work.
After all, an international shipping strategy does not end with delivery. It must also function when a customer returns their order.
How PARCEL.ONE supports shipments to the UK
International shipping processes run particularly efficiently when transport, customs clearance and data processing are coordinated. This is precisely where PARCEL.ONE comes in.
At our cross-border hub in Pohlheim, parcels are recorded, sorted and prepared for onward delivery via international delivery networks. Our multi-carrier infrastructure allows different shipping options to be organised centrally, without the need to set up separate operational processes for each target market.
For shipments to the UK, we work with our long-standing partner, MS Direct. This partnership combines our operational shipping logistics with specialised services for customs clearance, document management and international returns.
The result is a coordinated shipping solution in which technical interfaces and operational processes work seamlessly together. The services required depend on the shipping volume, product range and the individual requirements of the online retailer.
The aim: reduced operational complexity, clearly defined responsibilities and an international shipping experience that continues to function effectively even as parcel volumes increase.
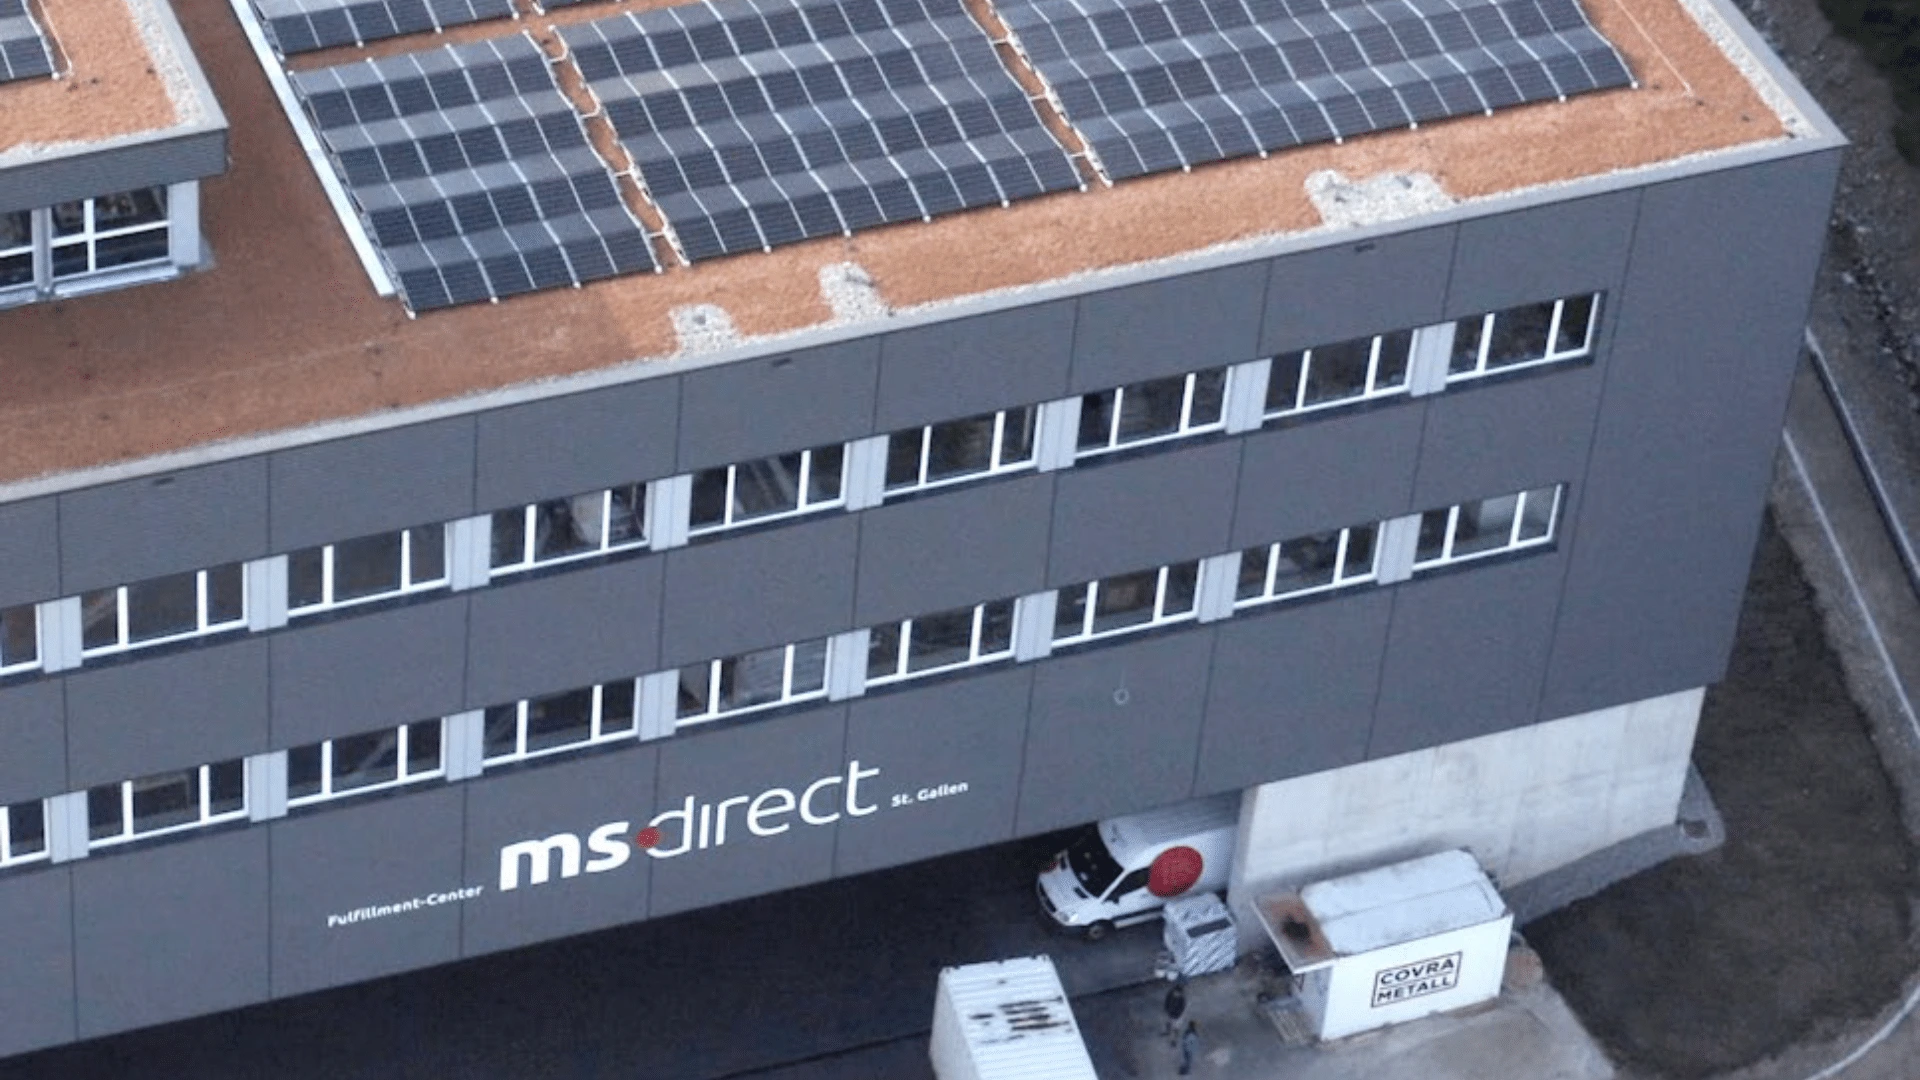 Photo: Copyright by MS Direct AG
MS Direct: Customs and returns for the UK
From customs clearance and document management to local returns processing: MS Direct complements our international shipping logistics with specialised services for the UK market.
Find out more about MS Direct and delivery to the UK →Checklist: How to prepare for shipping to the UK
Anyone who regularly sends parcels from the EU to the UK should clarify the key requirements before placing their first order. These six points will help you prepare:
- Check customs data: Are the descriptions of goods, tariff codes, values of goods and details of origin recorded in full and correctly?
- Clarifying tax obligations: How is UK VAT charged? Who is liable for consignments up to £135 and for sales via marketplaces?
- Taking import duties into account: Can customs concessions be utilised, and who is responsible for paying any duties and clearance charges?
- Co-ordinating dispatch processes: Have customs declarations, any necessary ENS notifications and data transfer with the relevant service providers been finalised?
- Providing customers with clear information: Are delivery times, any additional costs and parcel tracking explained in a way that is easy to understand?
- Organising returns: How are returns processed, and what customs requirements apply to re-importation?
It is the interplay between these elements that is crucial: when product data, customs clearance, transport and returns are coordinated, international dispatch processes can be made more reliable and efficient.
Frequently asked questions about shipping to the UK
Do I need a customs declaration for parcels sent to the UK?
Yes, customs formalities are generally required for regular shipments of goods from the EU to England, Scotland and Wales. These can be handled by a logistics or customs service provider. Not every parcel is physically inspected in the process.
What does the £135 limit mean for shipments to the UK?
For many direct B2C sales where the value of the consignment is up to and including £135, UK VAT is already charged at the point of sale. Above this threshold, the standard import procedures generally apply.
Are goods from the EU duty-free when sent to the UK?
Not automatically. The trade agreement between the EU and the UK allows for duty-free trade provided that the goods meet the applicable preferential rules of origin and the duty relief is claimed correctly.
What do online retailers need to bear in mind regarding returns from the UK?
Returns from the UK to the EU must be cleared through customs. Under certain conditions, returned goods may be exempt from import duties. This requires, amongst other things, appropriate supporting documentation and a correct customs declaration.
Conclusion: Shipping to the UK requires well-coordinated processes
Even five years after Brexit, the UK remains an attractive market for European online retailers. The additional customs and tax requirements make shipping more complex, but by no means unmanageable.
The key factors are accurate product information, transparent costs and a shipping solution that integrates customs clearance, transport and returns.
PARCEL.ONE helps online retailers to organise these processes efficiently in collaboration with specialist partners.
Would you like to optimise your deliveries to the UK? Let´s talk.